How to Reduce Variable Expenses Without Feeling Restricted
Reducing variable expenses does not require removing every comfort from your life. It means finding the flexible parts of your spending, deciding which ones still serve you, and adjusting the rest with a clear purpose.
That distinction matters because variable does not mean unnecessary. Groceries, fuel, household supplies, and some utility costs can change from month to month even though they cover real needs. Dining out, entertainment, shopping, and subscriptions may also be variable, but their value depends on how often you use them and what they add to your life.
A useful plan protects essential costs and the spending you genuinely value. It then reduces waste, unplanned repetition, and purchases that no longer match your priorities. The aim is not to create the lowest possible budget. The aim is to create more room for the goals, bills, and experiences that matter most.
This guide explains how to reduce variable expenses with recent evidence, flexible limits, practical substitutions, and a 30-day review process. You can use the method whether you want to create a small monthly buffer, prepare for a larger bill, or make an existing budget easier to follow.
Table of Contents
What Counts as a Variable Expense
A variable expense is a cost whose amount can change. Some variable expenses occur every month, while others appear only when you make a purchase or use a service. The amount may depend on consumption, frequency, price changes, timing, or personal choice.
If the distinction is still unclear, start with the Loyalix guide to fixed and variable expenses. A fixed cost is generally more predictable for a period, while a variable cost changes. The label describes how the amount behaves; it does not tell you whether the expense is good, bad, essential, or optional.
Common examples include:
- groceries and household supplies;
- fuel, public transport, parking, and occasional travel;
- electricity, heating, water, or mobile data when the bill depends on use;
- dining out, coffee, delivery, and convenience food;
- clothing, personal care, hobbies, entertainment, and gifts;
- subscriptions, app purchases, and usage-based digital services;
- medical, family, school, pet, and maintenance costs that do not occur at the same level every month.
Before reducing anything, separate necessary variation from avoidable variation. A higher grocery bill may reflect guests, dietary needs, or a price increase. A higher delivery bill may reflect a difficult workweek. Understanding the reason prevents you from treating every increase as a budgeting failure.
Why Extreme Cuts Are Difficult to Maintain
A strict plan can look impressive on paper because it produces an immediate savings target. The problem appears when the plan assumes that normal life will stop: no busy evenings, no social occasions, no replacement purchases, and no small comforts. If the plan leaves no room for those realities, one unplanned purchase can make the whole month feel unsuccessful.
Imagine that food delivery averaged 220 per month during the last three months. Reducing it to zero may save more in theory, but it also requires every meal to be planned and prepared. A target of 130, supported by two easy backup meals and one planned delivery night, may produce a smaller saving that is easier to repeat.
The stronger question is not, ‘How much can I remove immediately?’ It is, ‘What change can I repeat without creating a larger problem elsewhere?’ A grocery cut that leads to more takeaway meals is not a saving. A cheaper tool that creates hours of manual work may not be better value. The full effect matters.
A Six-Step Method to Reduce Variable Expenses
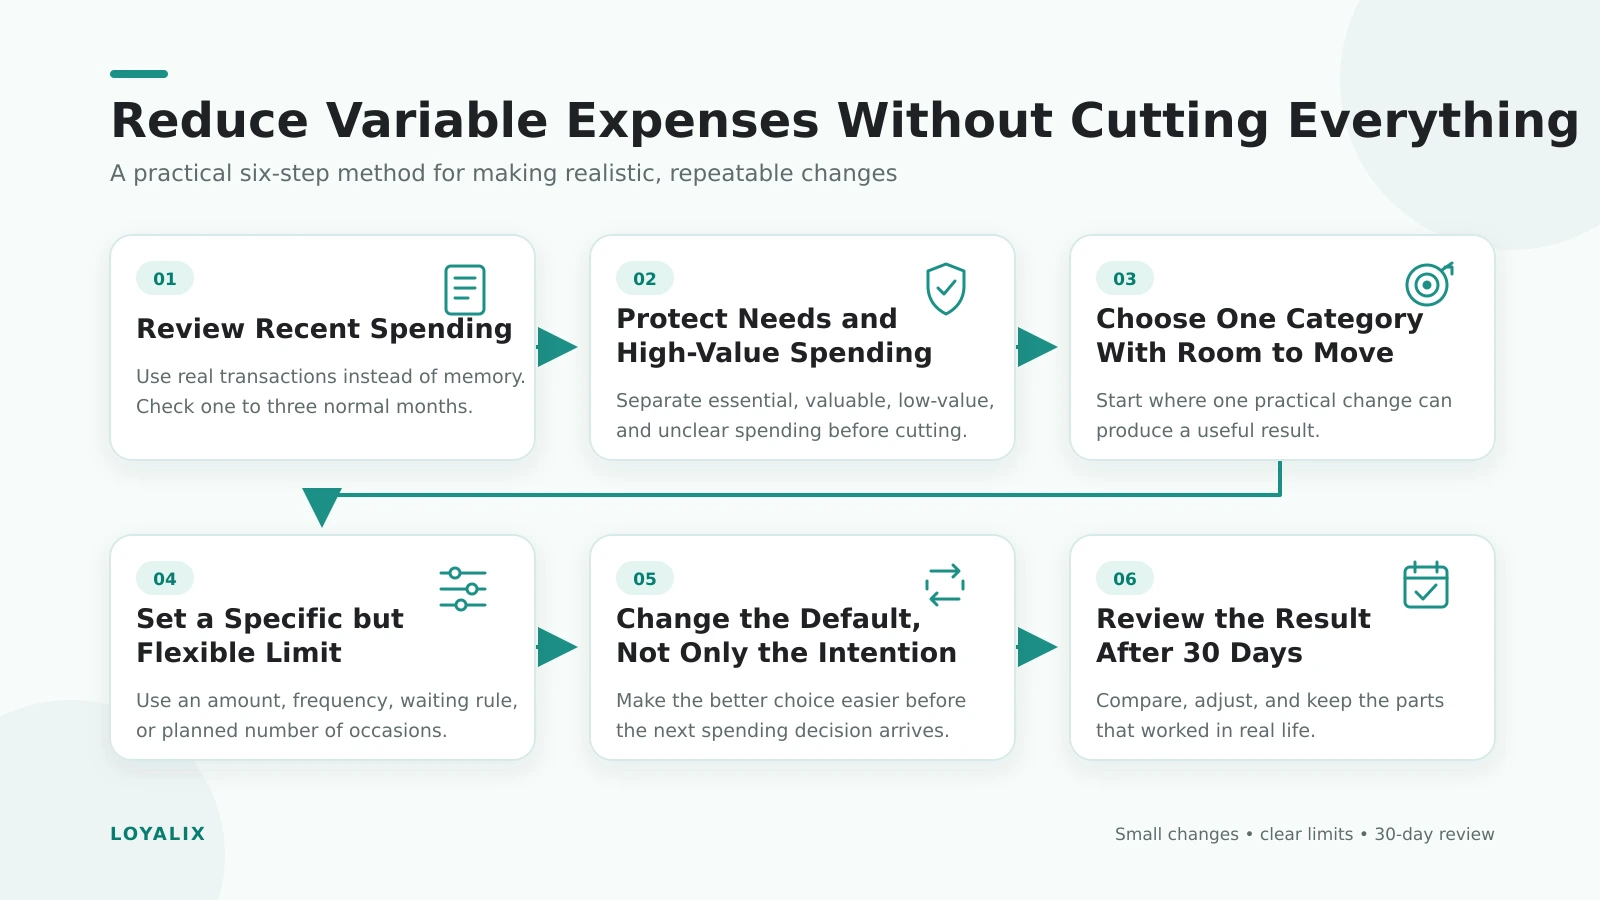
Step 1: Review Recent Spending Before Setting a Target
Use real transactions instead of memory. Review at least one normal month; two or three months are better when the category changes considerably. Check bank and card statements, payment services, cash notes, app stores, and receipts. Include annual or irregular charges separately so they do not disappear from the picture.
If tracking feels overwhelming, begin with the Loyalix guide on how to track your spending. The Consumer Financial Protection Bureau also suggests starting small and reviewing one week at a time when recording expenses feels difficult.
Step 2: Protect Needs and High-Value Spending
Mark each item as essential, valuable, low-value, or unclear. Essential spending covers needs and obligations. Valuable spending supports your health, relationships, work, learning, or daily routine. Low-value spending is easy to forget, repeat, or regret. Unclear spending needs investigation before a decision.
This step prevents price from becoming the only test. A modest subscription used every week may deserve to stay, while a larger annual plan with no current purpose may be the better place to act.
Step 3: Choose One Category With Room to Move
Choose a category that is large enough to matter and simple enough to change without disrupting essential needs. Good starting points often include repeated convenience purchases, unused subscriptions, unplanned shopping, or a category where several similar transactions appear each week.
You do not have to begin with the category that makes you feel most guilty. Begin where one clear change can produce useful information. Success in one category also makes the next decision easier.
Step 4: Set a Specific but Flexible Limit
Base the limit on your recent average and the behavior you are willing to change. Avoid choosing a number only because it looks disciplined. Decide what will be different: fewer purchases, a lower-cost version, a waiting period, or a planned number of occasions.
Example: If delivery averaged 220 per month, you might set a target of 150 and plan one order per week. The target is measurable, but it still allows convenience when you value it. A monthly target can also be converted into a weekly guide by dividing it by about 4.3. In this example, 150 per month is roughly 35 per week.
Step 5: Change the Default, Not Only the Intention
A target is easier to follow when the environment supports it. Remove saved payment details from shopping apps, prepare a short grocery list, keep one fast meal available, combine errands, turn off promotional notifications, or place a renewal reminder on your calendar.
The objective is to add a small pause between an impulse and a payment. That pause gives you time to decide whether the expense still fits the plan.
Step 6: Review the Result After 30 Days
Compare the planned amount with the actual amount, but do not stop at the number. Ask what created the savings, what created friction, and whether spending moved into another category. Record any one-time event that made the month unusual.
Keep the parts that worked. Change the parts that were inconvenient or unrealistic. A spending limit is a working decision, not a permanent judgment about what you are allowed to enjoy.
Flexible Limits That Leave Room for Real Life
Different categories respond to different kinds of limits. Choose the method that matches the way the expense occurs.
| LIMIT METHOD | BEST FOR | EXAMPLE |
|---|---|---|
| Amount limit | Categories with many small transactions | Set 150 per month for dining and delivery. |
| Frequency limit | Purchases that happen repeatedly | Buy coffee outside twice a week. |
| Waiting rule | Unplanned online or personal shopping | Wait 48 hours before a non-essential purchase. |
| Planned occasion | Social and convenience spending | Choose one delivery night and one meal out. |
| Replacement rule | Habits you want to keep in a cheaper form | Use the library before buying a book, then purchase it if needed. |
A limit should be clear enough to guide a decision and flexible enough to survive a normal month. If a category repeatedly exceeds the target, investigate the cause before making the number stricter. The category may be underfunded, prices may have changed, or the limit may not match how the household actually operates.
Practical Ways to Spend Less by Category
Groceries and Household Supplies
Start by reducing waste and duplicate purchases rather than cutting the food or household items you need. Check what is already available, plan several realistic meals, and build a list around ingredients that can be used more than once. Keep one or two simple backup meals for busy days.
Compare the total receipt, not only individual sale prices. A promotion does not save money when it adds an item you would not otherwise buy or when the product is wasted before it can be used.
Dining Out and Food Delivery
Separate planned enjoyment from emergency convenience. A meal with friends may be a valued choice; an expensive order made because nothing is ready at home may be a planning problem. Decide how many occasions or how much money you want to reserve for each.
A useful substitution might be one planned restaurant meal instead of several automatic purchases, collection instead of delivery, or a prepared meal from a grocery store instead of a full takeaway order. Include delivery charges, service fees, and tips when comparing the real cost.
Transport
Review the trips you can influence without creating safety or scheduling problems. Combine errands, compare parking options, plan fuel stops, or use public transport when it is genuinely practical. Do not assume the cheapest ticket creates the lowest total cost if it adds significant travel time, transfers, or another paid journey.
Shopping and Personal Purchases
Use a waiting period for purchases that were not planned. Save the item, leave the checkout page, and return after 24 or 48 hours. During the pause, check whether you already own something that performs the same job, whether the item solves a current problem, and whether the full price fits this month's plan.
Unsubscribe from promotional messages that create urgency. A discount only lowers the price of a purchase; it does not turn an unnecessary purchase into a saving.
Subscriptions and Digital Services
Review app stores, payment services, bank cards, and annual renewals. For each service, record its purpose, actual use, next renewal date, and cancellation terms. Consider downgrading, pausing, or replacing before cancellation when the service still performs an important job.
The U.S. Federal Trade Commission advises consumers to check trial and renewal terms, monitor statements, and keep cancellation records. Rules and consumer rights vary by country, so use the official guidance that applies where you live.
Entertainment and Personal Spending
Give enjoyable spending a defined place instead of pretending it will not happen. A personal amount can cover books, hobbies, coffee, small treats, or social plans. When the amount is planned, you can use it without treating every purchase as a mistake.
If the category runs out early, decide whether to wait, move money deliberately from another flexible category, or revise the next month's plan. Avoid quietly using money reserved for bills or essential needs.
A Realistic 30-Day Variable Expense Reset
A short experiment is often more useful than a permanent rule because it gives you a clear start, a review date, and evidence for the next decision.
Week 1: Observe
Track one selected category without trying to make it look better. Record the amount, timing, payment method, and reason for each purchase. Note whether it was planned, necessary, convenient, social, or impulsive.
Week 2: Change One Default
Choose one practical change: a grocery list, a delivery schedule, a waiting rule, a weekly allowance, or a reminder before a renewal. Keep the rest of the plan stable so you can see whether this change helps.
Week 3: Check for Friction and Displacement
Look for hidden consequences. Did fewer grocery purchases produce more delivery orders? Did a cancelled service create manual work or a new fee elsewhere? Did the limit protect your priorities or simply make the week harder?
Week 4: Compare and Decide
Compare the month with the original baseline. Keep, revise, or stop the experiment. Record the amount actually freed up and assign it to a purpose. Then decide whether to continue with the same category or move to another one.
Consumer.gov recommends making a spending plan at the beginning of the month, recording what you spend, and comparing the result with the plan at the end. Its budget guide provides a simple official reference for this monthly cycle.
Common Mistakes to Avoid
Treating Every Variable Expense as Optional
Food, fuel, medicine, utilities, and family needs may vary without being optional. Reduce waste and overpayment where possible, but protect the purpose of the expense.
Changing Too Many Categories at Once
When several rules change together, it becomes difficult to identify what worked. Start with one or two categories and use the result to guide the next adjustment.
Using an Unusual Month as the Baseline
Travel, visitors, medical needs, school costs, repairs, or seasonal bills can distort one month. Use several months when possible and label exceptional events instead of building a normal limit around them.
Counting a Cancellation Before Billing Stops
A cancellation request does not always mean the charge has ended or that the current period will be refunded. Save the confirmation, record the final access date, and check the next statement.
Moving the Cost Instead of Reducing It
A category can appear lower while total spending stays the same. Less dining out may be replaced by more premium groceries; fewer taxi rides may create parking or fuel costs. Compare the whole effect, not only one line in the budget.
Focusing Only on Tiny Purchases
Small repeat purchases deserve attention, but do not spend hours removing minor costs while ignoring a larger unused plan, repeated delivery fees, or a category that exceeds its target every month. Consider both the amount and the effort required to change it.
Give the Savings a Clear Purpose
Money that is no longer spent in one category can easily disappear into another unless you decide where it should go. Transfer the amount, record it in the budget, or assign it to an upcoming expense as soon as practical.
Possible uses include:
- a buffer for irregular household or transport costs;
- an upcoming annual bill or planned purchase;
- an emergency fund;
- debt repayment;
- a personal, family, education, or business goal;
- a category that was previously underfunded.
If the purpose is financial safety, the Loyalix guide to an emergency fund for beginners explains how to choose a starting target. If you need a broader structure, use the simple budget for beginners to connect variable spending with bills, savings, and income.
The amount does not have to be dramatic to be useful. A repeatable monthly saving can provide more value than an extreme one-time cut that is quickly reversed.
Final Thoughts
To reduce variable expenses without feeling restricted, begin with evidence rather than guilt. Identify what the spending does, protect essential and high-value choices, and select one category where a realistic change is possible.
Use a clear limit, change the default that drives the expense, and review the full result after 30 days. If the plan saves money without creating a higher cost or making daily life unnecessarily difficult, keep it. If it does not, adjust the method instead of treating the month as a failure.
The purpose of reducing flexible spending is not to make life smaller. It is to stop low-value spending from taking money away from needs, stability, and the choices you care about most.
Frequently Asked Questions
What are variable expenses?
Variable expenses are costs whose amount can change because of use, frequency, timing, prices, or choice. Examples include groceries, fuel, utilities based on use, dining out, transport, shopping, entertainment, and personal spending. Variable does not automatically mean optional.
Which variable expenses should I reduce first?
Start with a category that is large enough to matter, has clear room for adjustment, and can be changed without harming essential needs. Repeated convenience purchases, unused subscriptions, and unplanned shopping are common starting points, but the right choice depends on your own records.
How much should I reduce at first?
There is no universal amount. Use your recent average, choose the behavior you are willing to change, and set a measurable 30-day target. A smaller reduction you can repeat is more useful than a large target that shifts costs elsewhere or cannot be maintained.
Is there a recommended percentage for variable expenses?
No single percentage works for every household. Income, housing, transport, health needs, family responsibilities, local prices, and goals all affect the amount available for flexible spending. Build the limit from your actual budget rather than a generic ratio.
How can I reduce grocery costs without cutting essential food?
Focus first on waste, duplicate purchases, unused ingredients, and last-minute shopping. Check what you have, plan realistic meals, use a short list, compare total prices, and keep simple backup food available for busy days.
Are subscriptions fixed or variable expenses?
A subscription may have a fixed recurring price, but many people place it in a flexible or discretionary category because it can be changed or cancelled. Some services are essential or usage-based. The label matters less than recording the full cost, purpose, renewal date, and cancellation terms.
How often should I review variable expenses?
A brief weekly check can catch problems before the month ends, while a fuller monthly review shows whether the plan worked. Review annual renewals and irregular expenses before their deadlines instead of waiting for the charge to appear.
What should I do if I exceed a spending limit?
Identify the reason before changing the target. The limit may have been unrealistic, prices may have changed, an unusual event may have occurred, or spending may have moved from another category. Adjust the next decision and protect money reserved for essential bills.